Imagine you run a small business and a supplier wants payment within 48 hours. You own a Rolex Submariner worth about £12,000, but do not want to sell it. A regulated lender can turn that watch into same-day cash while you keep ownership, returning it once you repay.
That is the appeal. Watches, jewellery, and designer handbags can act as short-term financial tools when cash is tight and timing matters. And these agreements usually do not appear on your credit file.
I like this option when the need is clear, the timeline is short, and the repayment plan is realistic. Used well, it gives you breathing room without forcing a permanent sale.
What This Funding Model Is And Is Not
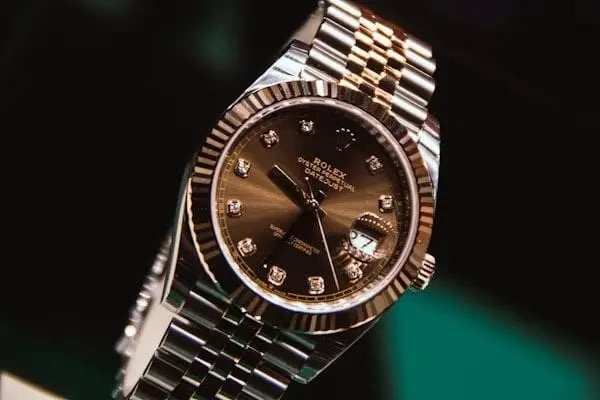
You hand over a luxury item, receive cash based on resale value. But the lender's claim is limited to the item you pledge.
Key terms to know: LTV, or loan-to-value, is the percentage of your item's market value you receive as a loan. Surplus is any amount left over if your item sells for more than you owe.
| Factor | Pawnbroker Loan | Unsecured Personal Loan | Auction or Consignment
|
|---|---|---|---|
| Speed | Same day | Days to weeks | Weeks to months |
| Credit check | ID and anti-money-laundering checks | Full credit assessment | None |
| Ownership | You retain ownership | Not applicable | Item is sold |
| Credit file impact | Typically none | Yes | None |
| Recourse if you default | Limited to the item | Debt recovery action | Not applicable |
The Process, Step By Step
Whether you walk into an Essex pawn shop or a regulated lender elsewhere in the UK, the process is broadly the same, and a clear paper trail makes each stage easier.
Step 1: Eligibility And Documents
Accepted items include watches, jewellery, designer handbags, and selected collectibles. Bring photo ID, proof of address, and any documents that support authenticity and condition.
Step 2: Valuation And Offer
Specialists authenticate the item and assess resale value. Across the UK, average LTV is around 50%, though highly liquid items may achieve more.
Step 3: Contract And Term
You will receive details of interest, fees, and terms. Most contracts run about six months, with options for early repayment or renewal.
Step 4: Custody And Storage
Your item should be sealed in tamper-evident packaging and stored in an insured vault. Ask for a condition report and receipt before leaving.
Step 5: Repay And Redeem
You can repay in full or on schedule. Early repayment reduces interest and returns your item sooner.
Step 6: If You Do Not Redeem
The shop must issue notice before selling. If the item sells for more than you owe, the surplus is returned to you. Sections 120 and 121 of the Consumer Credit Act 1974 govern this process.
Worked example: A £10,000 Rolex at 50% LTV gives a £5,000 loan. At 5% monthly interest, three months costs about £750, while six months costs around £1,500.
If you want a local comparison, read a concise provider FAQ on valuation, term length, renewal, notice periods, sale procedures, costs, storage standards, and your likely repayment timeline. Further reading is available at Essex pawn shop.
How To Choose The Right Provider
Pick a firm that is authorised, transparent, and secure.
- Confirm FCA authorisation on the public register
- Check for National Pawnbrokers Association membership
- Ask for rate tables or representative examples
- Request clear custody and insurance details
- Confirm how surplus payments are handled
- Ask about early redemption and renewal options
Questions to ask on your first call: What is the monthly rate? Are storage and insurance included? What happens if you renew? How is surplus returned?
Conclusion
Used carefully, luxury-backed borrowing can solve a short cash squeeze without forcing a sale. The process is simple, protections are clear, and good providers explain costs upfront. Prepare your documents, compare repayment figures, and ensure your exit plan is solid before handing over an item you value.
Copyright © 2026 California Business Journal. All Rights Reserved.
For California Business Journal Disclaimers, go to /terms-conditions/.


