Every month, millions of Americans open their credit card statements and feel the same sinking knot in their stomach. The balance never shrinks, and the interest never lets up.
Americans now carry more than $17 trillion in household debt, with credit card balances passing $1.3 trillion. Interest rates are hovering above 22 percent, and borrowing is more expensive than at any point in recent memory.
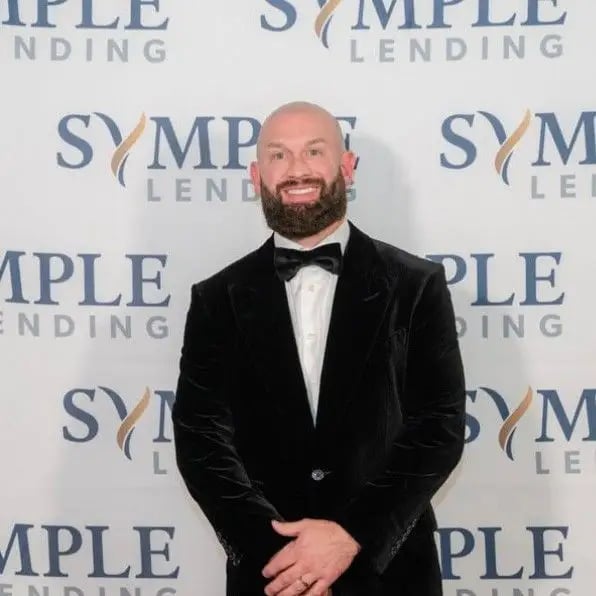
But according to Houston Fraley, founder and CEO of Symple Lending, one of the nation’s fastest growing financial lending firms, the numbers reflect more than just economics.
They represent the emotional burden debt places on ordinary people.
“Debt feels overwhelming because it’s tied to emotions like fear, guilt and uncertainty,” he explains. “But once you lay everything out, what you owe, what you’re bringing in, what options are on the table, things start to feel more manageable.”
The biggest mistake people make with their debt?
Fraley says it’s waiting too long to get help.
“Many people wait, not because they don’t care, but because they feel ashamed, afraid or simply stuck,” he says. “There’s a fear of judgment, of facing the numbers or of admitting that things have gotten out of control.”
The stress is real. It wears people down long before the numbers do.
“Shame doesn’t lead to better choices,” Fraley says. “It leads to avoidance. People might take out the wrong loan, delay getting support or stay in survival mode just to avoid feeling exposed.”
Biggest misconception?
“One of the biggest misconceptions is that debt consolidation is a sign of failure,” Fraley says. “Like it means you’ve mismanaged your finances or are taking a shortcut. But the truth is, choosing a solution like consolidating your many bills isn’t weakness; it’s being smart.”
Done responsibly, consolidation can simplify payments, lower interest rates and give families breathing room. Yet many avoid it because they’ve been conditioned to view it as a failure.
“Debt consolidation is not about giving up,” he says. “It’s about taking control.”
What trends are shaping consumer debt in 2025?
Credit card debt continues to grow to dangerous record highs, Fraley warns. Families are leaning on plastic just to cover the basics like groceries, utilities and even rent. In his experience, that’s a red flag. Short-term credit is filling long-term budget gaps and that rarely ends well.
He also sees a shift in how people view personal loans. Ten years ago, they carried a stigma. Today, they are widely used for debt consolidation. But if consumers don’t understand the terms or aren’t disciplined enough to avoid or control new debt, the best debt consolidation plans in the world won’t help in the long run.
Younger borrowers are shaping the picture, too. Millennials and Gen Z watched their parents struggle in past financial crises, and many are cautious about traditional credit cards. At the same time, they are quick to adopt digital-first lending platforms. The convenience is appealing, but Fraley sees the risk. Easy borrowing can lead to easy mistakes.
Put together, these shifts leave him convinced that 2025 is a turning point. Though debt is higher than ever, so is awareness. More people are open to solutions like consolidation and structured repayments. The challenge now is whether lenders will meet that openness with honesty and transparency.
Why don’t more people pursue solutions like consolidation?
Fraley believes it comes down to trust. “The biggest challenge facing the debt relief industry right now is trust,” he says. “For too long, people have seen hidden fees, misleading promises or programs that weren’t designed to succeed. That history makes them skeptical, and rightfully so.”
Many borrowers feel trapped between two bad options: continue struggling alone or risk getting burned by a company or program they don’t understand. That fear keeps them stuck, even when real solutions are available.
Red flag or green light? Spotting the difference.
“Red flags are easy to recognize if you know what to look for,” Fraley says. “Guaranteed approvals, vague promises and programs that seem too good to be true: those are warning signs. If a company isn’t transparent about the costs, or pressures you to sign right away, you need to walk away.”
How do you spot a trustworthy firm? “A good company is going to ask you questions,” he explains. “They’ll want to know your full financial picture, not just push a product,” “Transparency, education and options: those are the green flags. If you’re working with someone who takes the time to ask probing questions and answer yours, you’re probably in good hands.”
The future of lending
Fraley believes technology will play a big role, but it cannot replace human guidance. AI and digital platforms are making borrowing faster and easier, yet speed alone is not the answer. “Without guidance, fast decisions can quickly become bad ones,” he says.
What he sees defining the next era is personalization. People want solutions that fit their lives, not one-size-fits-all programs. That means lenders who educate, tailor and stay transparent will be the ones who last.
For Fraley, the real key is empathy. “Debt is emotional,” he says. “Automation can simplify the process, but only compassion builds trust.”
What’s the takeaway for 2025?
Fraley insists that while the numbers are daunting, the future doesn’t have to be.
“Debt is not destiny,” he says. “With the right plan, people can take control, lower their stress and start moving forward again. I’ve seen it happen hundreds of times. Change is possible, and it can start faster than most people think.”
The key is to do something about your debt, and the sooner the better.
“There are amazing solutions available to almost everyone,” he says. “Consolidation, structured repayment and budgeting support can turn something overwhelming into something manageable.”
Companies like Symple Lending are guiding people through that process with transparency and compassion. “You don’t have to do this alone,” Houston Fraley says. “The sooner you take the first step, the sooner that weight begins to lift.”
Copyright © 2025 California Business Journal. All Rights Reserved.
For California Business Journal Disclaimers, go to /terms-conditions/.


